Home · Services · Commercial Fire Damage
Commercial Fire Damage in Columbia, MD
Quick answer
Commercial fire work for Wilde Lake, Long Reach, and Harpers Choice, reopening scope separated from full restoration in Columbia, shaped by planned village homes and townhouse rows with shared assemblies where shared townhouse assemblies, duct carried soot, and association process drive the call pattern.
The Columbia read on commercial Fire Damage: planned village neighborhoods of single family homes, townhouse rows, and garden condos built from the late 1960s onward, with shared walls and roofs across much of the stock. Lake Elkhorn and the area's humid summers, cold winters with heating season fire load, and summer storms that open damaged roofs to rain decide what gets scoped first, and that order is written into the scope before anyone commits to a price.
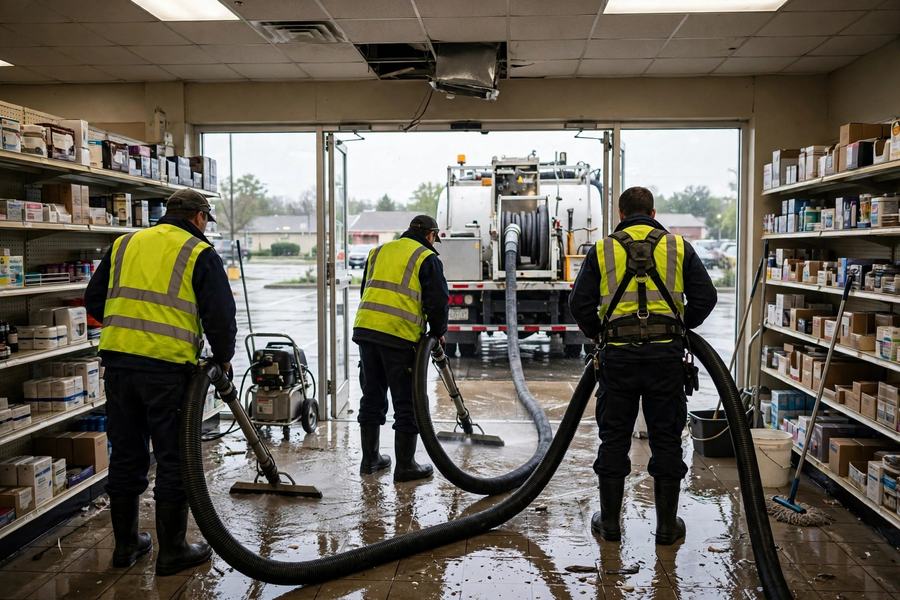
How we approach this job
Commercial documentation: For commercial fire damage in Columbia, the buying situation is a business or landlord decision: the scope, photographs, and timeline are written so managers, tenants, and insurers can act on them.
Signs you need commercial fire damage
- You are coordinating with your insurer, landlord, or tenants on next steps. It usually means city and insurer sign-offs pace the rebuild as much as construction does.
- Firefighting water damaged stock, equipment, or the unit below. It usually means the fire's water, not its flames, wrote this part of the loss; extraction and stock documentation start the recovery file.
- A fire closed your business, shop, restaurant, or rental unit. It usually means tenants, shared systems, and a reopening schedule are part of the scope.
- Smoke reached neighboring units or shared spaces. It usually means neighboring spaces carry smoke scope even without flame.
What the job involves
What affects the price
- Size of the space and how much of it burned versus smoked
- Stock and equipment value at risk
- Whether neighboring units are involved (shared walls, shared ducts)
- Code or inspection requirements before reopening
- Downtime, which is why sequencing and documentation speed matter as much as cleaning
When it is an emergency
For a business, the emergency is measured in days closed. Secure the property the night of the fire, notify your insurer immediately, and do not discard damaged stock before it is documented, however unsavable it looks. Photograph everything first.
PLACEHOLDERCommercial Fire Damage across the Columbia area
Related services
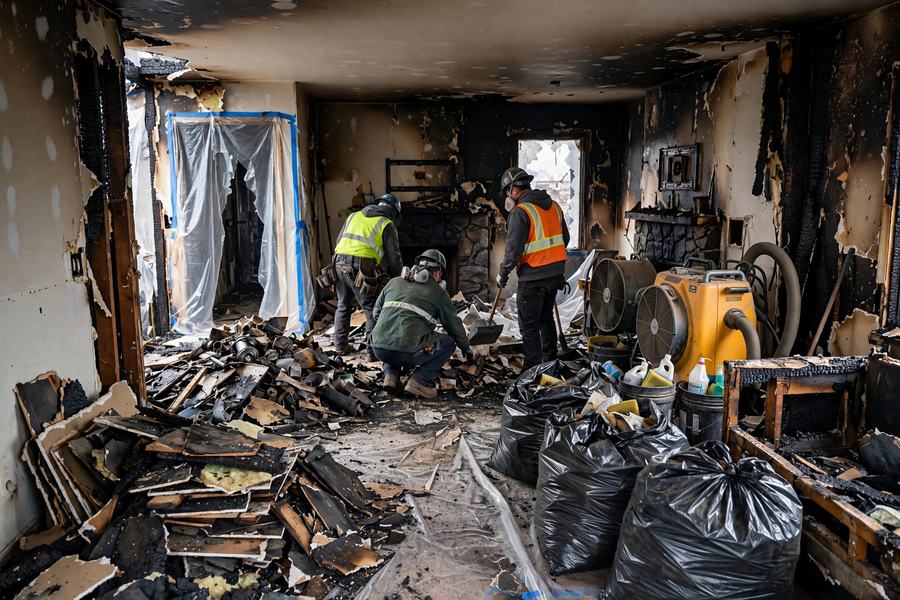
Fire Damage Restoration
Fire restoration in Columbia that reads the whole building: fire unit, shared systems, and the neighbors the smoke and water reached in Columbia, shaped by planned village homes and townhouse rows with shared assemblies where shared townhouse assemblies, duct carried soot, and association process drive the call pattern.
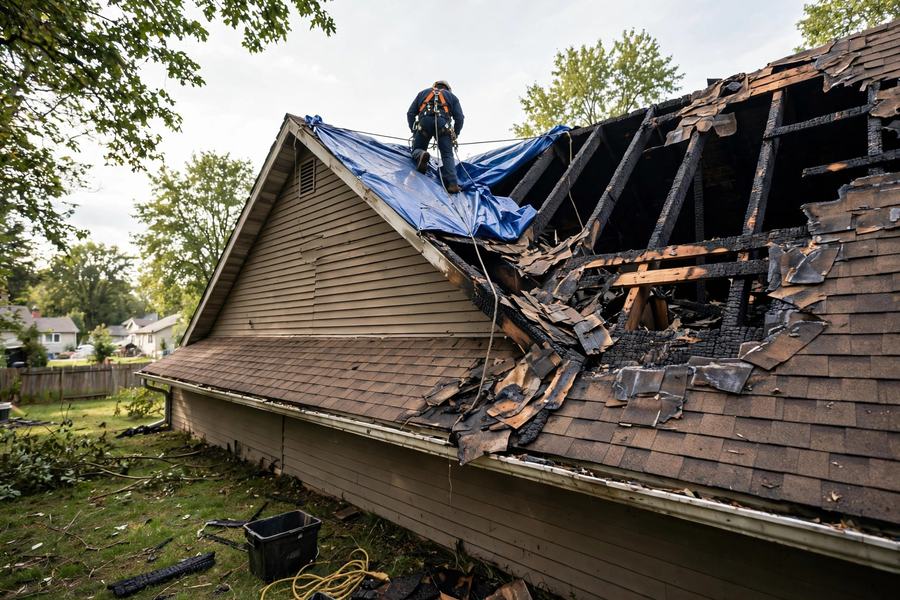
Emergency Board Up and Tarping
Board-up in Columbia secured to a storm standard, photographed before and after for the claim and the building in Columbia, shaped by planned village homes and townhouse rows with shared assemblies where shared townhouse assemblies, duct carried soot, and association process drive the call pattern.
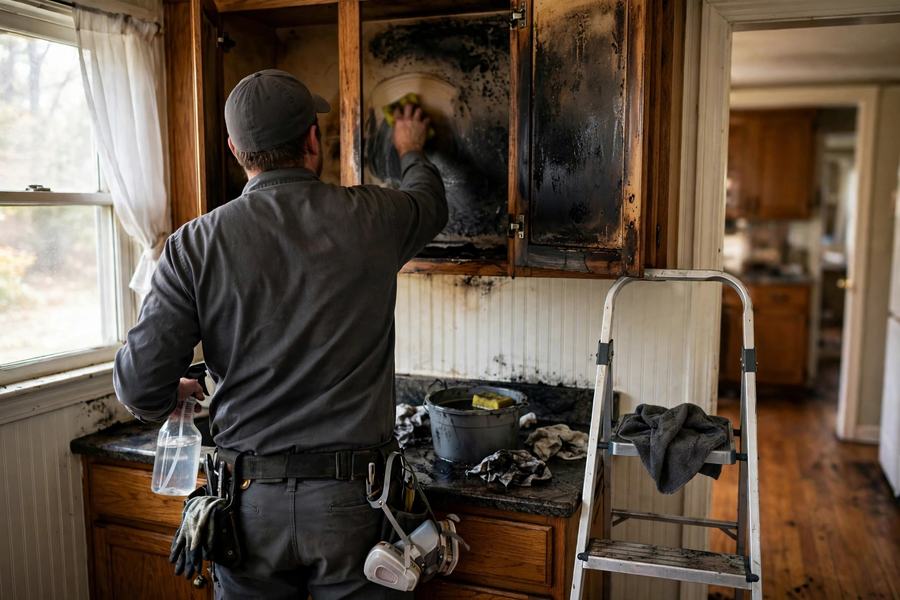
Smoke Damage Cleanup
Smoke cleanup in Columbia scoped along the path smoke actually took: corridors, chutes, and shared air, unit by unit in Columbia, shaped by planned village homes and townhouse rows with shared assemblies where shared townhouse assemblies, duct carried soot, and association process drive the call pattern.
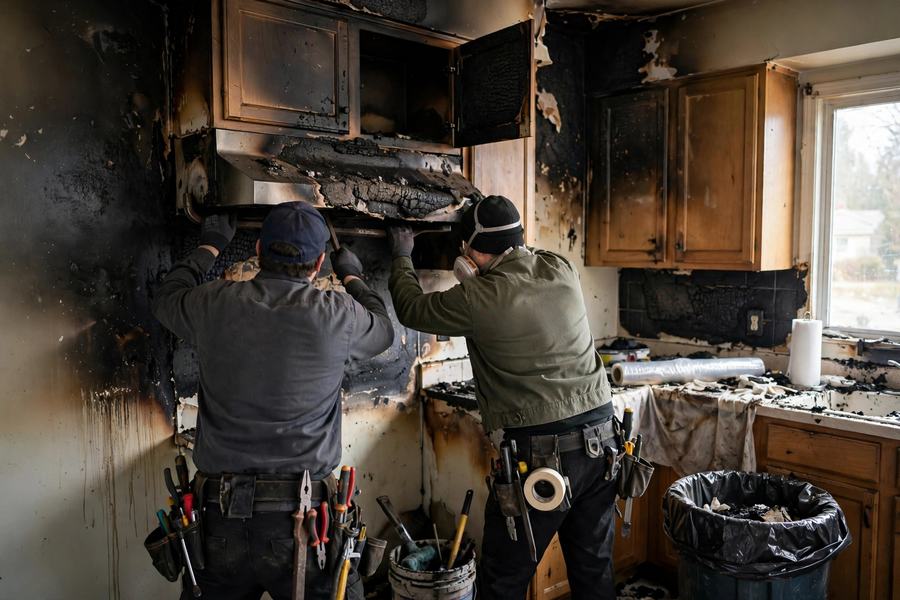
Kitchen Fire Cleanup
Kitchen fire cleanup in Columbia naming the soot type, the sprinkler water path, and the corridor as one event in Columbia, shaped by planned village homes and townhouse rows with shared assemblies where shared townhouse assemblies, duct carried soot, and association process drive the call pattern.
Commercial Fire Damage questions, answered
When is commercial fire damage an emergency?
For a business, the emergency is measured in days closed. Secure the property the night of the fire, notify your insurer immediately, and do not discard damaged stock before it is documented, however unsavable it looks. Photograph everything first.
What affects the price of commercial fire damage in Columbia?
The main price factors for commercial fire damage are covered in the cost section above. The contractor confirms the exact price in a written estimate after seeing the job, and nothing is owed until you approve it. The call and the referral are free.
Will insurance pay for temporary housing after a fire?
Usually yes, if your policy includes loss of use (Coverage D), which most standard homeowners policies do. It pays the additional living expenses of being displaced, hotel or rental, and the increased cost of meals and essentials, up to your policy limit, while the home is uninhabitable due to a covered loss. Keep every receipt from the first night. If the home is habitable after the assessment, loss of use generally does not apply, which is one reason the habitability decision gets documented carefully.
What is board up and why does it have to happen the same night?
Board up is securing the home after the fire: fitted boards over broken windows and doors, and tarps over roof damage. It has to happen the same night for three reasons. Weather through a broken roof or window turns a fire loss into a fire plus water loss by morning. An open, visibly damaged home invites entry and theft. And insurers expect the property to be protected from further damage as a condition of the claim. The board up work is photographed and becomes part of your claim documentation.
My Columbia condo had a fire. Whose insurance pays, mine or the building's?
Both, in layers set by the association documents: the master policy typically covers the structure and common elements, and the unit owner's policy covers the unit's interior finishes, fixtures as defined in the documents, and contents. The documents, not the adjuster's first impression, draw the line, so obtain them in the first week and keep every scope written against that line.
Request a callback
Prefer to talk later? Leave your details and an independent local pro will call you back. No charge to you, no obligation.
Lake Elkhorn Fire Restoration is a free referral service. Submitting this form connects you with independent local contractors who provide the work.